Artificial Intelligence
Competition Among China’s AI Models Is Intensifying as the Chip Sector Advances
- A key question for investors is how AI-model developers can sustain model leadership and differentiate themselves from each other as competition intensifies.
- Investors are increasingly focused on the “harness layer”—the ecosystem that houses AI models.
- China’s semiconductor sector is ramping up faster than the market expected, though bottlenecks persist.
- Chinese open-weight AI models are being adopted around the world, in some cases housed on Western cloud-computing systems.
The competition between makers of China’s artificial intelligence (AI) models is intensifying, raising questions among investors on the sustainability of leadership in model performance, with increasing focus on cost efficiencies and the harness layer. At the same time, the country’s capacity for building semiconductors is showing signs of exceeding investor expectations, according to Goldman Sachs Research.
Those insights were among the discussions at the second annual Goldman Sachs Asia Leaders Conference in Hong Kong, the firm’s largest client gathering in the region. The event featured companies that form the entire AI supply chain: 400 companies were represented and over 1,400 investors attended the event in Hong Kong.
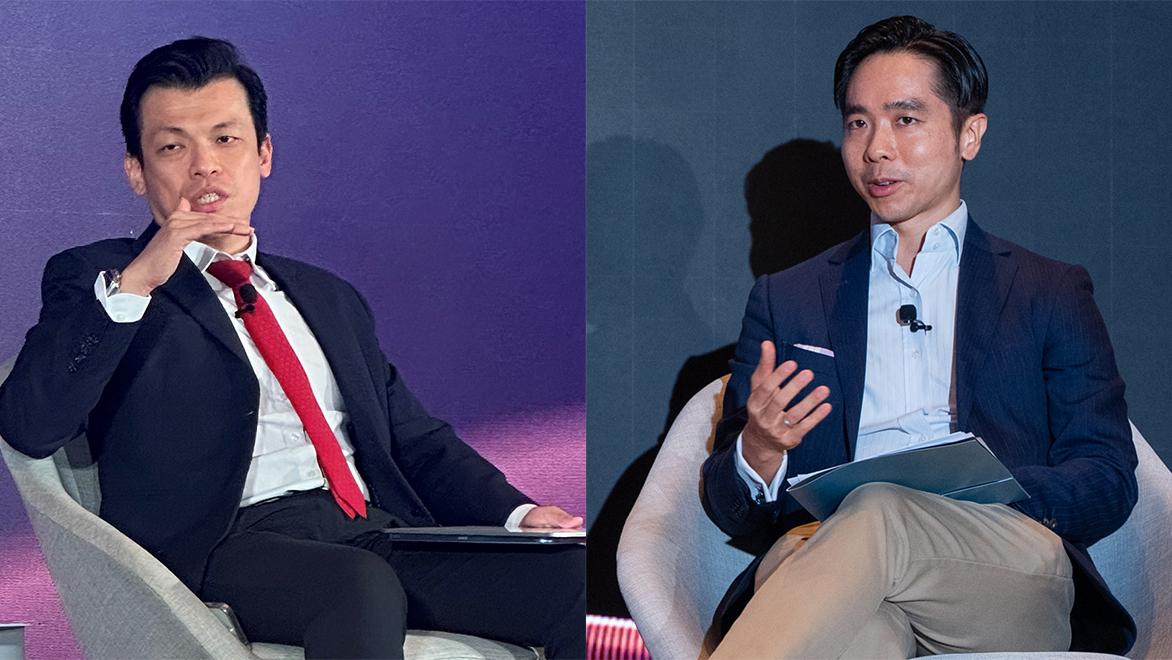
In many cases, the gap in performance, especially in coding, is narrowing between the leading AI models, says Ronald Keung, head of the Asia Internet Research team.
“Intense competition on the model layer brings investor questions as to how AI-model developers can differentiate besides model performance,” Keung says. “The key may be in cost efficiencies and on the harness layer.”
The harness layer refers to the ecosystem that houses and enables AI models. The harness allows the model to, among other things, access data and follow workflows. “The next key investments are focused more on the harness layer,” Keung says. “The AI labs in China actually are just beginning harness investments. In the past, the Chinese AI labs were more focused on the model layer.”
What is the outlook for China’s semiconductor industry?
Conference participants were also focused on China’s semiconductor sector, says Allen Chang, head of the Greater China Technology Research team. Officials in Beijing aim to increase the country’s self-sufficiency in AI and semiconductors. “There's always a lot of debate on China semiconductors,” Chang says.
He says the development of China’s semiconductor industry—which includes chip design, tools for semiconductor manufacturing, silicon wafer fabrication, and the manufacturing of specialized AI chips—is progressing faster than he and the market expected.
“The progress has surprised the market,” Chang says of China’s semiconductor industry. He points out that the local leading chip foundries in China have larger capacity expansion plans than analysts expected. At the same time, the semicap equipment makers (the tools for making semiconductor chips) have issued guidance for 40% year-on-year revenue increases over the next few years.
Investors have noted that more of the makers of specialized computing chips for AI, the GPUs and ASICs, are listing shares on the public market, Chang says. “That’s why they need to announce their volumes in terms of production as well as technology migration,” he says.
But even as the semiconductor industry advances, Chang says there are still bottlenecks—principally in the availability of GPUs. “Everything is driven by the GPU computing power.” And while there’s been progress, there are still constraints in terms of local foundry capacity and semicap equipment, he adds.
How big is the market for optical networking?
Optical networking was another part of the AI ecosystem that was in focus at the conference, Chang says. Networking unlocks computing capability for AI chips and enables data exchange at low latencies. While copper cables and printed circuit boards are commonly used for short distance connections within servers, optical fiber connections have higher performance for long-distance or high-speed interconnections, according to Goldman Sachs Research. Our analysts expect the total addressable market for this technology to increase by nine times to $154 billion in 2028.
Chinese AI models are being adopted around the world
As the technology advances, investors may not fully appreciate the success that Chinese models have had in proliferating around the world, Keung says. While China’s AI technology faces geopolitical scrutiny in some jurisdictions, adoption is ongoing.
He notes that Chinese open-weight large language models (LLMs) are being housed on US hyperscaler cloud systems, which could mark a step forward for these models reaching larger markets. By keeping their data and computing on domestic servers, countries with higher security thresholds could allow the use of Chinese AI models. “We're seeing that as an interesting development,” Keung says.
In the meantime, China’s AI companies are taking different approaches to creating a competitive advantage, Keung says. Some are pushing for premium frontier status—to create the most advanced models—while others are attempting to be more cost efficient. “What the labs are trying to aim for is the best price-to-performance ratio,” he says.
“Our view is the combination of these elements will lead to pricing power,” Keung says. “Cost efficiencies and the strongest financial power will lead to the most lasting success.”
This document has been prepared by the Goldman Sachs Executive Office and is not a product of Goldman Sachs Global Investment Research. The opinions and views expressed herein are as of the date of publication, subject to change without notice, and may not necessarily reflect the institutional views of Goldman Sachs or its affiliates. The material provided is intended for informational purposes only, and does not constitute investment, legal, or tax advice, a recommendation from any Goldman Sachs entity to take any particular action or be used as a basis for any other investment decision, or an offer or solicitation to purchase or sell any securities or financial products. Any forward-looking statements, case studies, computations or examples set forth herein are for illustrative purposes only. Past performance is not indicative of future results. Neither Goldman Sachs nor any of its affiliates make any representations or warranties, express or implied, as to the accuracy or completeness of the statements or information contained herein and disclaim any liability whatsoever for reliance on such information for any purpose. Each name of a third-party organization mentioned is the property of the company to which it relates, is used here strictly for informational and identification purposes only and is not used to imply any sponsorship, affiliation, endorsement, ownership or license rights between any such company and Goldman Sachs. This material should not be copied, distributed, published, or reproduced in whole or in part or disclosed by any recipient to any other person without the express written consent of Goldman Sachs.
Subscribe to Briefings
Our weekly newsletter delivers the latest insights on economic forces shaping markets—from Goldman Sachs leaders, economists, and investors around the world.
You can unsubscribe at any time. For information about how your personal data will be used, visit Privacy Information and Resources.