Chairman and CEO David Solomon Joins CNBC from Our Builders and Innovators Summit
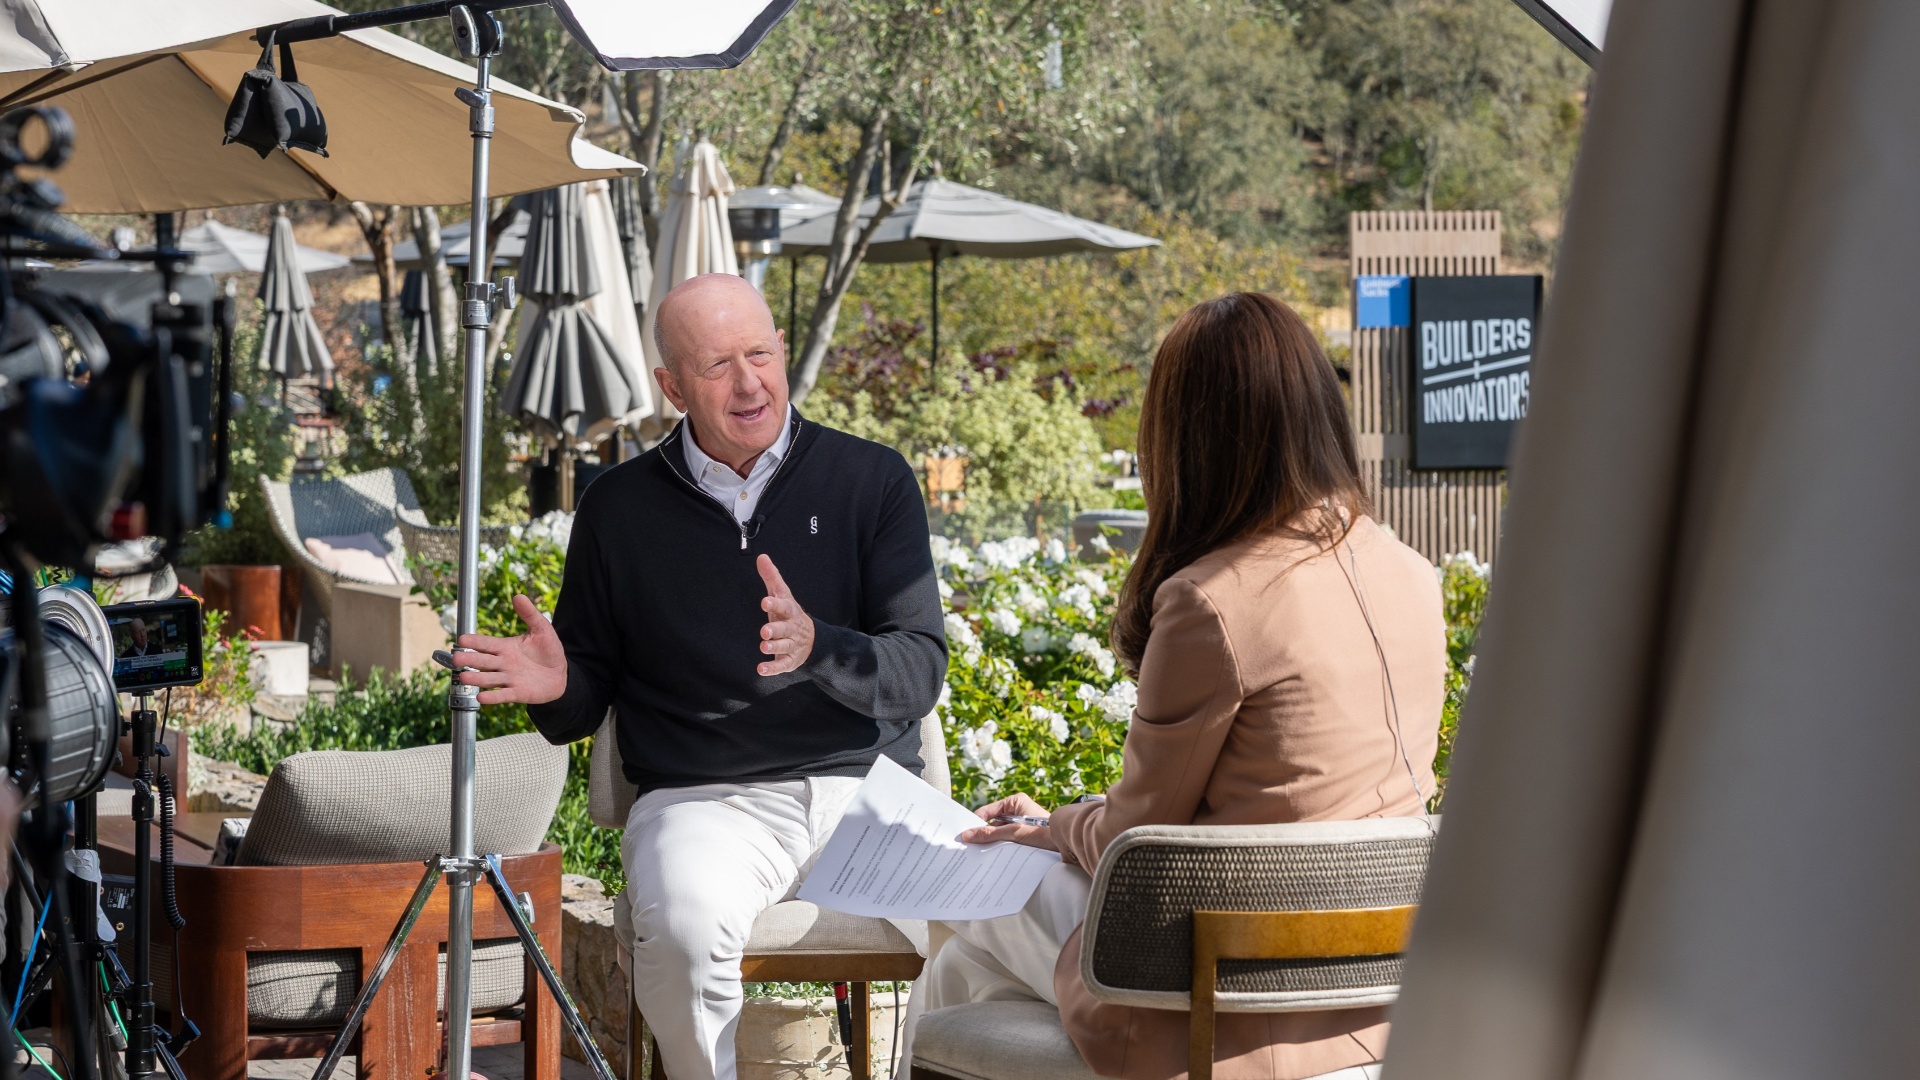
David Solomon discussed the firm’s third-quarter earnings, his outlook for near-term dealmaking activity, and continued confidence in the IPO market. He also shared his views on AI innovation, and the need for human and enterprise accountability and risk controls.
Transcript:
Kelly Evans: Let’s begin with one of the standout bank names so far this earnings season. Increasingly so, as we see the raft of results today: Goldman Sachs. Yes, it’s down 2% in sympathy with other financials, but they reported their second-highest quarterly revenue ever yesterday. Earnings per share were $2 higher than the highest Wall Street estimates. Equities trading, investment banking, and wealth management all posting big year-over-year gains. Joining us now to weigh in on that, on what’s happening with AI financing, perhaps inflation, and so much else, Goldman Sachs CEO David Solomon. And amid some speculation about his potential replacement, by the way, he’s out at Goldman’s Builders and Innovators Conference in San Francisco with that lady right there, Kate Rooney. Kate, over to you.
Kate Rooney: Kelly, thank you so much. We are here with David Solomon. It’s great to see you in person. Thanks for having us. We’re at the Builders and Innovators Summit. You were just saying, 15 years now. Is this the 15th year?
David Solomon: Well, first of all, Kate, thanks for being here. And this is a pretty great spot. It’s a nice place for you and I to have a day to be here and do this. But a little more than 15 years ago, we created this conference. The idea was to bring together really interesting entrepreneurs that were doing fascinating things and building interesting companies. I go back 15 years and I think about Travis Kalanick from Uber. I think about Dropbox. I think about Matthew Prince from Cloudflare. Drew Houston from Dropbox. These were some of the early entrepreneurs. They built great big companies. And here’s another class of 150 that are coming today. Some of these will be companies that, 10 years or 15 years from now, we’ll talk about. It’s been a fascinating place to see innovation and kind of the real engine of the U.S. economy and U.S. innovation.
Kate Rooney: We want to get your take on the pipeline. It’s a great setup. But Kelly mentioned earnings. You guys are coming off one of your strongest earnings reports in the firm’s history. I wonder about durability, though. You talked on the analyst call about volatility helping you guys, this tech supercycle as you described it. What is the earnings engine going forward for Goldman if things start to change or rates really start to take a bite here?
David Solomon: I think one of the things that’s missed in the narrative of day-to-day reporting and trading is that we’ve been working for eight years to really grow our franchise and increase the durability of our revenues and the diversity of our business. When we started eight years ago, we had a little less than $5 billion in management fees in our asset and wealth management business. We had $3.6 billion this quarter. We’re on a run rate of $15 billion in management fees. We have built now a firm where 45% of revenues are considered durable, recurring revenues.
Now, of course, when you look at IPOs and M&A activity, there’s a little more cyclicality around those activities. But go look at M&A revenues for the last 15 years. Every year there’s M&A revenue, some years more than others.
So we have a big, durable, diverse business in global banking and markets and asset and wealth management. And what we’ve done strategically as a firm is we’ve significantly lifted the floor of our business, both in terms of the revenue base and also the returns. I think investors are seeing that and rewarding that, and we feel very good about it.
I can’t tell you what’s going to happen in the next three months or six months. I actually look out and see some very big equity deals coming. I see some potentially very big IPOs coming. I look at our M&A backlog. We said on the call yesterday our backlog is still at very, very robust levels. I feel very good about revenue accruals we have coming in M&A. I also see the strategic activity and dialogues that are going on, and I feel pretty good about it.
Counter to that, we saw a slightly hot inflation print today. There are obviously four interest-rate hikes baked in. When you look forward, the 10-year Treasury has moved kind of 75 basis points in the last quarter and people are concerned about that. But we can operate in this environment pretty well, and we are operating well. We’ll just have to keep, quarter after quarter after quarter, showing people that our firm is a big, diverse, durable firm.
Kate Rooney: Well, one of the things you said on the call was that 5% on the 10-year didn’t scare you. What is the number that would make you nervous?
David Solomon: It’s all got to be put in context. But my point was, if you step back, the anomaly is the last 15 years after the financial crisis.
Kate Rooney: The record low.
David Solomon: Interest rates. That’s the anomaly. I mean, I’ve been around for 64 years. The anomaly is zero interest rates, not a 5% 10-year Treasury. Obviously, significant moves when they happen quickly upset markets and can have an impact. But you’re seeing the world absorb this move in the 10-year Treasury reasonably well.
Now, if you continue to have pressure because of deficits, the fact that there is big demand for capital, I think one of the things that’s going on is there’s a lot of demand for capital for this AI cycle, and that’s also competing with the fact that governments have borrowed very aggressively. There’s a lot of demand for capital for government. So there is some pressure around that that affects rates.
But I’m not scared about all this. This is the environment we live in and we operate in.
Kate Rooney: Well, one of the things that is different, I mean, you look back 20 years and sure, rates were the same, but the amount of AI capex that is now reliant on debt is very different than what we’ve seen in the past. We had Broadcom’s CEO recently saying that he thinks capital could be the biggest constraint and really a potential choke point for this entire buildout. What do you make of that?
David Solomon: I saw his comments. I have a different point of view. My point of view is there’s a lot of capital in the world. Think of the size of the market cap of public equities in the world. Think about all the savings that exist in the world. Think about the wealth that exists in the world. There’s a lot of wealth in the world.
That doesn’t mean that everybody that has an idea, everybody that has a data center, everybody that has a chip, can have unlimited capital at a very, very low cost to pursue their aspirations.
At the end of the day, capital is disciplined. It looks for returns. It goes to the best opportunities.
I would just say there’s a lot of capital out there. The financing markets, particularly in this country, the capital markets are extraordinary and developing new ways to access capital and package capital. I think some of the things we’re talking about doing right now, and our partnership with NVIDIA around compute, are super interesting.
Is there a crowding-out effect that at the margin affects the cost of capital a little bit? Absolutely. But that doesn’t mean the capital is not available. For good projects and good returns and good opportunities, there’s plenty of capital in the world.
Recorded on October 14, 2026.
The opinions and views expressed herein are as of the date of publication, subject to change without notice, and may not necessarily reflect the institutional views of Goldman Sachs or its affiliates. The material provided is intended for informational purposes only, and does not constitute investment advice, a recommendation from any Goldman Sachs entity to take any particular action, or an offer or solicitation to purchase or sell any securities or financial products. This material may contain forward-looking statements. Past performance is not indicative of future results. Neither Goldman Sachs nor any of its affiliates make any representations or warranties, express or implied, as to the accuracy or completeness of the statements or information contained herein and disclaim any liability whatsoever for reliance on such information for any purpose. Each name of a third-party organization mentioned is the property of the company to which it relates, is used here strictly for informational and identification purposes only and is not used to imply any ownership or license rights between any such company and Goldman Sachs.
A transcript is provided for convenience and may differ from the original video or audio content. Goldman Sachs is not responsible for any errors in the transcript. This material should not be copied, distributed, published, or reproduced in whole or in part or disclosed by any recipient to any other person without the express written consent of Goldman Sachs.
Subscribe to Briefings
Our weekly newsletter delivers the latest insights on economic forces shaping markets—from Goldman Sachs leaders, economists, and investors around the world.
You can unsubscribe at any time. For information about how your personal data will be used, visit Privacy Information and Resources.